Sunday, April 10, 2016

The (boring) secret to being rich.. And how to fund a brilliant idea

It's not what you earn, it's what you spend. 

I came across this quick article, which led to a bunch of related videos and topics. http://time.com/money/4034098/get-rich-secret/?xid=time_socialflow_facebook 

..and it's true!  The bigger the gap between what you make and what you spend, defines whether you are rich or poor. Live below your means. Live within a budget that balances, that includes a large chunk for saving as well. 

Now, if you have a goal or an idea (like any of these people on Dragon's Den for example), by all means pursue it!.. Within your means. Don't be the person going hundreds of thousands in debt for an idea, keep working or work harder to be able to fund the goal. 

I'm a big fan of the crowdfunding ventures. I support a bunch of things on Kickstarter, which is a place for artists, designers, writers, videographers, inventors and more to get their brilliant ideas funded. They offer their product or item at an extreme discount, and in various packages, to the general public with an end goal in mind. People like you and me can then go on and browse all the ideas and contribute (or buy into, literally) someone's idea to help them reach their mark. You only get charged your pledged amount if they reach their goal. I'm a supporter of a few different people and ideas, and for the most part I do it not for the item but for the person or the goal. You can also help fund a person for $1 or $5, just to track the progress of the great idea/product through the campaign and to market. I've done this too if I have no need for the item but think it's a great idea that should get funded. 


One of my favourite buys from Kickstarter and I'm going to give them a shameless plug have been the Fire & Bone team, who digitally scan animal bones and create metal mini molds of them for jewellery. I've bought way too many at this point but I think they are so incredibly cool (my favorites are the Dire Wolf and the Lynx/Bobcat) 
My other shameless plug will be a project I have waited and watched for more than a couple years called PillowTalk, which is a bracelet and speaker that shares your heartbeat with someone that isn't near you. My long distance fiancé and I kinda can't wait for this little contraption!

Other crowdfunding outlets exist, like GoFundMe which is more the everyday person hoping to fund their next computer purchase or their aunts medical bills, and Teespring which are for awesome designs on tshirts. I've been on both these sites, and other than the high shipping costs for the item we chose on Teespring, they were easy to contribute/buy. 

The secret to being rich is simply put, living within your means without debt. This all circles back to how to save money everyday, how to save for retirement and an emergency, and being surrounded by (and able to care for) the things you love. 

Friday, April 8, 2016

Broke/Budget maxed out?

So you a stretched for cash, or used up all the money from your budget jars... But you still need to eat and have fun? Here are some thoughts and solutions I've done when my wallet was hurting:

- Dig deep in the freezer!  Wow, what a treasure trove!  Frozen veggies and some meat you got on sale one time are probably down in the abyss, under all the ice cream and frozen bananas. Easy, multi meals are just a defrost away. 
- dig around in the pantry. Cans of mixed veggies and beans can be a good start to a crock pot meal. Rice and pasta are usually stored in a corner and make large portions for cheap. If there's a craving for a dessert item, how about a box of cake mix and a can of pop (yes this works beautifully!), which saves the cost of cookies or doughnuts. 
- gift cards. I still have gift cards from like 2 Christmases ago. This might be cheating, but for my birthday and Christmas I just ask for gift cards. Mostly food, I can usually buy some large meal out to get a couple work lunches out of the deal too. Gift cards are great for entertainment too - use one for a good sale rack shopping trip in a store, or to buy a DVD for later. 
- parents or grandparents visit. Again, cheating probably, but maybe see if you can stop by for a visit to loved ones. I don't think I've ever made it out of their homes without a meal (either eaten there or sent with me in a doggie bag)! I've never had to do it, but if you needed a couple meals to tie you over for the month, your family is sure to help you out with either made or almost-made meals if you just ask. 
- discount sections of grocery stores. There are usually a couple racks of the "almost expired" food stuff that is great to cook up the same night. We usually buy our meat here and then freeze it. You can usually get bread, fruits, veggies, pies, buns, meats and others for nearly nothing. I've done this before with hot dogs (buns and weiners were on for half price) that we cooked up and had the same night. 
-coupon. Follow the Facebook groups and blogs in your area who post about the deals, and jump on a great deal if you can afford to. If you're in my area, I like the Savings Guru, who posts all sorts of deals. He does the work for you and you just go out and get the free butter, or the cheap eggs that are on that week. 
- use your points. You've been accumulating points on your various cards for years, spend them when you run out of cash! Gas, shoppers drug mart, PC groceries, air miles, etc. You can also sometimes buy gifts cards for other places with your points, just have a look through your wallet for all your points cards and see what is available.
- look up free event days. In my area, the local skating rink will have free skate hours, and sometimes museums will have a special free day. I haven't done a lot of research in this area but there are groups and blogs about this topic too I've seen, as parents are always looking for cheap things to do with the little ones.
- regrow table scraps. This could be for fun, or for continuous small bits of food. This one doesn't need a lot of explaining, and it actually works
- throw a party! This sounds a little backwards, but if you do it right it can both be entertainment and extra meals. Make it a BYO drinks, food and chairs, and advise you'll provide the bathroom, music/movies, plates and cutlery. Have a good time with friends, watch a movie marathon, and have a day of fun that doesn't cost people very much to participate it (just a bowl of chili and a case of pop each basically). 
- make crafts. There are so many great YouTube tutorials and Pinterest things about crafts you can make for nothing. Repurposing garbage items, making string from plastic bottles, using various items as stamps, origami of old chip bags, you imagine it and someone has made a craft around it. This is a good option for families with kids. Just pick an item and google it with the word craft. I did soda can crafts and holy cow, cooool!!
- sell stuff. You meet people, it can get you out of the house, and it'll get you a little extra cash quickly that you can go to that discount food section with. Try selling old clothes, an old kitchen item, shoes, books, kids toys, puzzles, etc. you could also try selling your newly made soda can crafts and who knows, maybe there's a business idea in here. 
- while on this topic, what about making a little mini business out of something easy? I recently found out that I am good at string art, and actually enjoy all the hammering (stress relief) and stringing (relaxing). It's a minimal investment (I have to buy $2 roll of string, a $2 box of nails and a few brackets to hold wood together at the back (about $1 each), plus find an old wooden pallet to break up). But.. I could sell it for upwards of $20 and offer custom options. (The ones below were for my mom for Christmas (which had a dog saying added to the blank area in sharpie) and the logo of a company that was visiting my work's head office)

There are tonnes of other ideas, but this post is long enough with all the pics. What other tips do you use? 

Making a Budget - pt 2: The Emergency Fund

Part of your budget needs to have a healthy chunk going towards an emergency fund. My parents have a couple names for this bucket including "Mad Money" (which must be a movie reference or something), I call it my "high interest account", but whatever you want to call it, this is money you never touch. It is the just-in-case money that pays for a new roof (and allowed me to pay for mine all by cheque at once and get a hefty discount), it is the money to pay for a sudden pet's illness, and it should be one of your first major focuses if you don't have one yet. 

Even if you have consumer debt with high interest you need to pay off, you STILL need to put money into this locked and no-touch account though. Money should go into this account and basically never come out, so allow for it in your budget at whatever amount you can actually afford. Before you cut the savings allowance in your new budget, cut the clothing budget or substitute two meals a week for canned soup from the back of the pantry!

If you have debt, hunkering down and holing up to spend every penny possible on this high interest oopsie is even more important. Still save, but instead spend 3 committed months to eat out of the freezer, watch Youtube tv shows instead of going to the movies, use those gift cards you got last Christmas for entertainment/food, and spend every penny getting rid of that useless and ever-growing debt. I read a great blog entry I should have saved which was basically a couple who "disappeared" for 3 months in order to pay down $8000 of debt - they didn't eat out, they sold whatever they could, they picked up odd jobs, and they actually paid off all that debt with just 3 months of being absent from the social world. 

I mentioned eBay moments and side hustles in my first budget blog, and above in that couples 3 month dedication... So you've made a budget that is based on your fixed income, what do you with all the extra money (hopefully!) that is above and beyond?Instead of taking any extra money and spending it on a home decor item or a dinner out to celebrate, put it towards your future (I know, I'm a killjoy). Boost the savings account that month or pay a little more on the credit card. You can never have enough savings!


Now there are a bunch of Pinterest "schemes" of how to save money without realizing it - such as the "every $5 bill you get you save away instead of spending", or the "week 1, put away $1, week 2 put away $2", and you can read a bunch of blogs and stuff with other examples to get the idea. These might work for some people, but to be honest, they are hard to maintain, remember, AND budget for. If you are just getting started with budgeting, start squirreling away a set amount each week and month for your savings account. You can plan around this far better, and if you set it up as an automatic transfer on payday you won't even notice (which is what I do and strongly suggest).  If you want to do one of these other saving schemes, feel free, but it should come out of your after-savings budget if that makes sense (so outside of that automatic transfer). I do this too with any change that is in my pocket by the end of the day, and at the end of like 6 months I have enough to get a great dinner out (at like East Side Marios where I can get 2-3 meals out of one order with their unlimited soup/salad and bread!), or enough to buy a souvenir at my next little mini vacation. It's not much, and I don't notice it daily, but since this is already after my $25 automatic transfer to my savings account, I feel like I can "splurge" a little with this "found money". 

The moral: Don't skimp on your savings. Make this a number you are proud of, and feel safe with, should anything go wrong. 


Monday, April 4, 2016

Making a Budget -part 1

"You're telling your money where to go, not wondering where it went" - BudgetGirl on YouTube


So my mom sent me links to watch this lady on YouTube, and I invite everyone to watch a few of her videos. She covers food grocery trips, meal plans, general spending and general questions. She has student loans and a tight budget (plus she's funny). Or.. Check out Youtube while you're there for millions of other budget videos and tips. 

Before watching her, I went to a new bank to take advantage of a 3% 90day GIC they have available for a limited time last week (since extra money is better in my pocket than my other banks), and the advisor I got was really impressed with how financially secure I was at my age. Both BudgetGirl and this bank interaction has led to this post. 

Make a budget. Everyone. Know where you have the money to spend, so you know when you shouldn't be spending any more. 

This topic came up with my best friend who wanted to get a car. His current budget didn't really allow for a car (it did, but basically only for the yearly insurance cost and nothing else). In order to afford a car, he needed to rework his budget and his numbers. Does he cancel his gym membership or his soccer team playing fees? Does he cut out eating out completely instead? Does he get a second job instead? All of these and more were things to consider. 

While I'm giving some back stories, let me say that I have no debt other than my mortgage. This for me is an accomplishment at only 26. I have a car, a house, a dog, completed renovations with a new roof+furnace+air conditioner+water heater+finished basement, a fiancĂ©.. And I am able to eat, drive, work and play without debt. It is all thanks to budgeting (and couponing in part). 

My dummies guide to budgeting is a simple starting point. Read and Google all sorts of others, because having more to work with can never hurt. When I was getting started, I read everything I could and researched researched researched. 

Another good tool for me was Gail Vaz-Oxlade and her "life pie" I think it's called. This is a great guide for everyone, not just people who are in debt like her shows suggest. Her life pie tells you what percentage of your income should be going where at max.
 If your numbers in one area are out of whack, you need to adjust the other areas to balance. She's a huge promoter of the budget binder and the jars/envelopes method. She has a TON of resources on her website and she's a great first stop 
http://www.gailvazoxlade.com/resources/interactive_budget_worksheet.html
http://www.gailvazoxlade.com/resources.html


So, a budget? A budget is simply a way to manage your spending and not go into debt. It takes your income and divides it into quadrants of life to make sure that you can eat, drive, live and save, without spending money you don't have. 

Start with tracking your spending for 2-3 months. 1 month of spending might not get every bill you have for the house, or every expense like shampoo you don't need that month. Write everything down. Literally. Just write down what every single penny of your spending is going to. And don't just say "$2.00, gas station" write down what it was. There are a lot of apps that you can track this info in, but even just opening your notepad on your phone might be easiest. At the end of this time (or the end of each month), sit down with either an Excel spreadsheet or a big piece of paper, and start transcribing all of that info over into columns:   Food/drink,  fixed housing costs (you can't change them like the mortgage amount),  variable housing costs (like the electric bill),  transportation (from the CAA card to bus tickets),  entertainment (eating out tends to go here),  baby/child/pet costs, home decor/Reno,  savings (generic saving, retirement savings, automatic deductions),  and you can change these depending but I usually call them Bath & Body (like hair products, soap, shavers) and Home Essentials (toilet paper, cleaners, tin foil, etc). 

Total up your columns and then look at anything else you haven't figured yet....  For me I literally went through item by item what I would need. Like a car, in a year I would need wiper blades, oil changes, tire rotations, new tires every few years, new lightbulbs every few years, car cleanings, gas weekly, windshield washer fluid, CAA emergency roadside, insurance, license plate renewals and stickers, replacement parts/fixing/just in case fund. I googled the numbers for these items and wrote them in my budget. I did the same thing for the house, outdoor maintenance, the dog, myself, my health (what is and isn't covered by my work), gifts and birthdays, what I normally spend at Christmas, vacations, work-sponsored donation days, etc. 

Look at other website budgets too for anything you might have missed. A good starting point was this post. http://www.midgetmomma.com/2015/01/15/20-things-you-are-forgetting-to-put-in-your-budget/

Take your $ numbers and scale them up to show a year. If you buy gas weekly, x52 weeks. If you buy shampoo once every three months, x the number by 4. If you need tires every 3 years, take the cost and divide by 3. 

Once you have a final number in every category, divide it by 12. This will give the average cost of that column by month, and this is what you should be squirreling away each month to afford that item later. 

There is a TON of work that can be done here, so make sure you budget (hah, get it) a bunch of time to do it right. 

Then look at your income. Is it fixed? Variable? Different income types will call for different budgets in some cases, but I always suggest you have some sort of fixed income portion - maybe that's a paper route or a couple evenings burger flipping, but at least have some sort of predictable every month income budget amount. Write down the "take-home" pay, this is after the government takes their cut and the employer takes out the employee benefits information, and is what you actually have to work with. Maybe you have side jobs and eBay moments, great! But for the budget I would suggest sticking with some sort of concrete number you can bank on, so to speak. 

Add up all the columns in your tracking sheet, and compare that against your take home income. How far out are you? Look at Gails life pie and calculate the % numbers to see where you are spending too much money. She divides stuff into fixed expenses (things you can't change the payment amount of ) and variable expenses (everything else). If your fixed expenses are too high, then you have a hard decision to make of either generating more income or changing where you live/what you drive. Typically, everyone's variable expenses are way over budget too when you first make the budget. 

Work with the life pie idea and your income. How much should you be spending in each area? Work backwards if it's easier and then compare against your current spending. 

Then.. Cue the couponing aspect. If your variable transportation costs are too high, consider asking for CAA or wiper blades for your birthday. Think about carpooling options, buying gas in the middle of the week, home washing and cleaning. Where can you save money and eliminate it from your budget?

I know this was a long post so I'll leave it here for now. Get creative, do the research, ask for help. Especially if you have debt, you absolutely need to budget to be able to pay it off and avoid paying all those extra and unnecessary interest fees. Feel free to post any other good tips you have :)

Saturday, March 5, 2016

Staying (& Getting) Motivated to Save

This is a topic that has been on my mind lately. I think it is easy to get lazy, get discouraged, get overwhelmed, and all sorts of other things that distract from couponing or saving money. 

We get busy with work. 
We get "busy" with relaxing.
We get discouraged with a lack of deals. 
We forget the coupon binder at home. 
We get that craving for fast food...

I've been guilty of all these, and personally for me they seem to do a snowball effect of happening together and one after the other. Some weeks I can be super good and a super dedicated saver, and then some weeks I just give up and buy the pre-made dinners and order pizza for dinner without a sale or coupon in sight. 


So how can you re-motivate yourself? For me, the best way has been to get "safe" results. 
-use a coupon. It doesn't matter for what, just use a coupon on something. That usually gets the ball rolling 
-request coupons and send feedback to companies. When I get those high value "thank you" coupons in the mail, it kinda feels like Christmas and re-motivates me to try and do a great savings shopping trip. 
-take inventory of what I have and need, then take that to the Flipp flyer search app to see which of those items are on sale
-browse the blogs and Facebook pages for the deals posted by them. There will usually be at least one item that has been posted that I can go out and get 

Another great way to stay motivated for me is to not stop. Literally, don't take a hiatus from couponing and just keep doing a sprinkling of items at every shopping trip. Or simply actively searching the rebate apps and the front page flyer specials usually keeps me motivated enough to continue every week - wondering when I can score the next big deal! I also keep motivated and active by spending my lunches entering contests and requesting free samples. Not a lot of effort and when items come in the mail, they spark me on to continue. 

Something I kinda wish I had to keep me motivated? A support team! A team of couponing crazies that will share and mentor and suggest the great deal they found that week. I think that's why I write in this blog, just to feel like I am mentoring myself a little. I enjoy the social media couponing blogs and Facebook deal pages I hop on a few times a day, as in an odd way they feel kinda feel like they're talking to me to keep me going. 

Im open to suggestions and thoughts of how you staying in the "saving mindset" too. There's lots of ways and certainly every person is different, so feel free to share!


Wednesday, March 2, 2016

My last shopping trip - free is good!

My last shopping trip was pretty fun so just wanted to share it here. I went with my roommate and we both spent $50 each. It was kinda fun to see the differences!

Him:
Meat meat and meat
Pizza
Lettuce
Rice
.28 cent noodles
Canned Beans for a chili
Orange juice
Chips
And Shreddies which we price matched for $1.88

So, he got food. $50 doesn't go very far for food anymore it seems, so this was actually really good as it was a week if lunches basically. 

Mine:

3 bags of price matched smartfood ($2 each!)
2 bags price matched Tostitos 
Milk (we go through one of these bags a week)
Pop pop and cans of pop (altogether like $5)
New Nestea blackcurrent pop and coupon
Chocolate milk
.28 noodles and 2 cans of Italian wedding soup
Lemon liquid
2 bottles of laundry detergent which was price matched, couponed AND rebate app'd
2 bottles Vim which were price matched and couponed
1 bottle Palmolive which was price matched and couponed
2 vileda scrunge boxes plus a coupon
Restoralax bottle and coupon
Frank's Red Hot sauce and a full value rebate form filled out
2 Crunch bar sets and a coupon
2 bundles of organic bananas for $1 (clearance rack but they are perfectly fine!)

So from all this, I got free stuff!:

The Tide deal was probably the best as it was a money-maker. I price matched it for 3.99 each, then used a coupon that was $5 off when you buy 2. On top of this, Tide was also on one of the rebate phone apps for buy 2 and get $5. I have requested that cheque in the mail now!

The vileda scrunge and the Vim were coupons for buy one get one free. Great deals when the items go on sale. 

Restoralax coupon was for the full value of the item, after I wrote in to the company saying I liked their product  

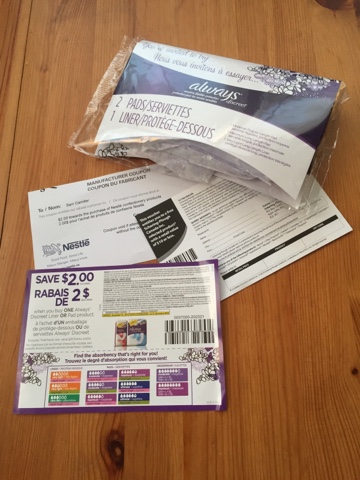
The two Crunch bars were a coupon from Nestle when I wrote in complaining about some really funky Smarties I bought (and didn't eat). They sent me a $2 off coupon, which I used on 2 $1 Crunch bar packages. You can see below the coupons, plus a free sample and coupon I received in the mail the same day. 


The Frank's is a current promotion for a full value rebate of any of their bottles. We were out so it was great timing!

Then yesterday I dragged my roommate out after work to grab something else we are out of: bottled water. 

The store had a one day only deal coupon which I pulled from the web and printed. They have their case of 24 waters on sale for $1.97 (which in itself is a good deal), but the coupon gave a buy one get one free. We walked out of there with 4 cases of water for under $4. 

Something to note for the word "free" though..  Usually you still need to pay the tax. Unless the coupon states otherwise, tax is not included. For the restoralax and the 2 crunch bars which I did in one transaction, I still had to pay $1.53 I think it was. All for the tax man. 

Happy shopping!

Sunday, February 14, 2016

"Sad coupon day": The monthly binder clean out

Just a quick entry about an important half hour you should spend one day every month: checking your coupon expirations. 

Coupons typically work for around 3 months. If it's a high value or free product coupon, it might be less. In some cases too, a free product or $ value credit (like if you call Nestle to complain about a product, they might send you "$5 to spend on any nestle products" coupon) will last for a year. Fast food coupons tend to be the shortest - the good ones last for only a week. 

There are tips from other bloggers about arranging your binders/boxes/envelopes in order of expiry dates, instead of by products like I do. Maybe experiment and see what will work best for you. 

Regardless though, you should spend about a half hour every month just going through the book and clearing out the old expired coupons or the ones that will expire in a few days. I call it my "sad coupon day" - it almost feels like I am throwing out money! My last batch clean out was the end of 2015 and nearly a completely emptying of my entire binder!

There are opportunities to get these coupons used though instead of throwing them out. I've heard of people going out to a grocery store and placing the coupons that will expire soon on top of the products at the store. You could also jump on local Facebook groups and post about what coupons you have available for anyone that will buy that product. There are also things called coupon trains, where a line of people will place unwanted coupons in an envelope and ship it to the next person in line who will take out any coupons they want and replace them with ones they don't want and ship on to the next. 

In about this same time, it's also good to have a quick look through the pantry and fridge at expiry dates on your packaged goods and cheeses and such. Maybe that will plan the dinners for that week!